
125+ Florida Homeowners Insurance Quotes: Compare Rates & Save Money
Florida homeowners pay some of the highest home insurance rates in the country. Hurricanes, older roofs and storm claims push premiums up fast.
This guide gives you 125 sample Florida homeowners insurance quotes by city, coverage and savings tip. Use them to compare rates and save money. The figures are illustrative estimates, not live offers. Your homeowners insurance quote will depend on your ZIP code, roof and dwelling coverage.
Table of Contents
Florida Homeowners Insurance Quotes by City and Home Value
Home insurance rates in Florida change from one city to the next. Coastal areas cost more because of hurricane and wind risk.
Here are sample yearly premiums for three dwelling coverage limits in ten cities. Rates are highest in South Florida and along the Gulf Coast.
[copy]Miami, $350K home: about $5,400 a year.[/copy]
[copy]Miami, $500K home: about $7,600 a year.[/copy]
[copy]Miami, $750K home: about $11,200 a year.[/copy]
[copy]Fort Lauderdale, $350K home: about $5,100 a year.[/copy]
[copy]Fort Lauderdale, $500K home: about $7,200 a year.[/copy]
[copy]Fort Lauderdale, $750K home: about $10,600 a year.[/copy]
[copy]Cape Coral, $350K home: about $4,700 a year.[/copy]
[copy]Cape Coral, $500K home: about $6,700 a year.[/copy]
[copy]Cape Coral, $750K home: about $9,900 a year.[/copy]
[copy]St. Petersburg, $350K home: about $4,300 a year.[/copy]
[copy]St. Petersburg, $500K home: about $6,100 a year.[/copy]
[copy]St. Petersburg, $750K home: about $9,000 a year.[/copy]
Inland and northern cities usually cost less. They sit farther from the storm surge zone.
[copy]Tampa, $350K home: about $3,900 a year.[/copy]
[copy]Tampa, $500K home: about $5,500 a year.[/copy]
[copy]Tampa, $750K home: about $8,100 a year.[/copy]
[copy]Sarasota, $350K home: about $3,700 a year.[/copy]
[copy]Sarasota, $500K home: about $5,300 a year.[/copy]
[copy]Sarasota, $750K home: about $7,800 a year.[/copy]
[copy]Orlando, $350K home: about $3,000 a year.[/copy]
[copy]Orlando, $500K home: about $4,300 a year.[/copy]
[copy]Orlando, $750K home: about $6,300 a year.[/copy]
[copy]Pensacola, $350K home: about $2,700 a year.[/copy]
[copy]Pensacola, $500K home: about $3,900 a year.[/copy]
[copy]Pensacola, $750K home: about $5,700 a year.[/copy]
[copy]Jacksonville, $350K home: about $2,500 a year.[/copy]
[copy]Jacksonville, $500K home: about $3,600 a year.[/copy]
[copy]Jacksonville, $750K home: about $5,300 a year.[/copy]
[copy]Tallahassee, $350K home: about $2,100 a year.[/copy]
[copy]Tallahassee, $500K home: about $3,000 a year.[/copy]
[copy]Tallahassee, $750K home: about $4,400 a year.[/copy]
Published averages vary a lot. One recent analysis found Florida homeowners pay about $5,838 a year for a $300,000 policy. Another study put the 2025 state average at $8,292, with a 2026 forecast of $8,458. Methods and home samples differ.
Here are sample quotes by home value and home type.
[copy]Statewide, $250K home: about $2,400 a year.[/copy]
[copy]Statewide, $350K home: about $3,300 a year.[/copy]
[copy]Statewide, $500K home: about $4,700 a year.[/copy]
[copy]Statewide, $750K home: about $7,000 a year.[/copy]
[copy]Statewide, $1 million home: about $9,300 a year.[/copy]
[copy]High-value home worth $1.5 million: about $14,500 a year.[/copy]
[copy]Condo unit (HO-6) with $60K in belongings: about $900 a year.[/copy]
[copy]Landlord policy (DP-3) on a $350K rental: about $4,200 a year.[/copy]
[copy]Mobile home worth $120K: about $3,100 a year.[/copy]
[copy]Second home worth $400K: about $4,800 a year.[/copy]
Florida Homeowners Insurance Quotes by Coverage and Add-Ons
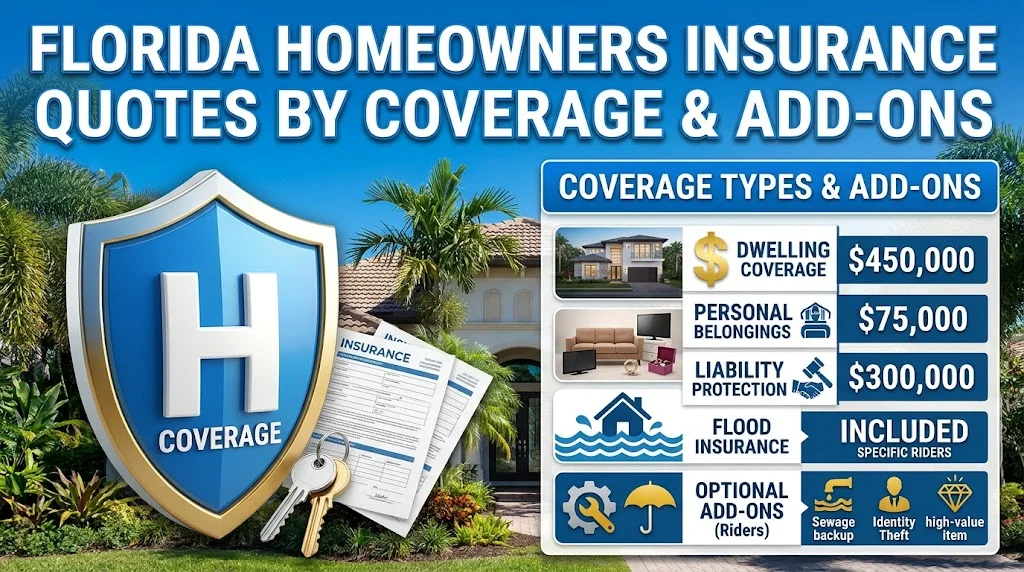
A standard HO-3 policy covers your home, your belongings and your liability. Add-ons raise the price, but they close costly gaps.
Most agents suggest other structures coverage at about 10% of your dwelling limit. Personal property is often 50%, and loss of use is often 20%. Here is how each piece changes a $350,000 policy.
While comparing Florida homeowners insurance quotes can help you protect your property and gain financial peace of mind, life’s challenges sometimes call for emotional strength, too. Explore these healing inspirational quotes for hope and inner peace to find comfort, encouragement, and renewed positivity during difficult times.
[copy]Dwelling coverage of $350,000 on a 2,000 sq ft home: about $3,300 a year as the base premium.[/copy]
[copy]Other structures at 10% ($35,000): usually included in the base premium.[/copy]
[copy]Other structures raised to 20% ($70,000): adds about $60 a year.[/copy]
[copy]Personal property at 50% ($175,000): usually included in the base premium.[/copy]
[copy]Personal property raised to 70% ($245,000): adds about $90 a year.[/copy]
[copy]Replacement cost on belongings instead of actual cash value: adds about $70 a year.[/copy]
[copy]Loss of use at 20% ($70,000): usually included in the base premium.[/copy]
[copy]Liability of $100,000: usually included in the base premium.[/copy]
[copy]Liability raised to $300,000: adds about $25 a year.[/copy]
[copy]Liability raised to $500,000: adds about $60 a year.[/copy]
[copy]Medical payments of $5,000 instead of $1,000: adds about $10 a year.[/copy]
[copy]Extended replacement cost of 25% above the dwelling limit: adds about $85 a year.[/copy]
Standard policies leave out flood damage, storm surge and most mold claims. The Insurance Information Institute explains these limits. Add-ons fill the gaps.
[copy]Ordinance or law coverage at 25%: adds about $110 a year.[/copy]
[copy]Water backup of $5,000: adds about $60 a year.[/copy]
[copy]Water backup of $10,000: adds about $95 a year.[/copy]
[copy]Fungi and mold coverage of $10,000: adds about $120 a year.[/copy]
[copy]Sinkhole coverage on a Tampa Bay area home: adds about $350 a year.[/copy]
[copy]Sinkhole coverage on a Central Florida home: adds about $250 a year.[/copy]
[copy]Sinkhole coverage on a low-risk coastal home: adds about $120 a year.[/copy]
[copy]Flood policy with a $250,000 building limit in a low-risk zone: about $600 a year.[/copy]
[copy]Flood policy with a $250,000 building limit in a high-risk zone: about $2,200 a year.[/copy]
[copy]Flood contents coverage of $100,000: adds about $450 a year.[/copy]
[copy]Scheduled jewelry worth $10,000: adds about $130 a year.[/copy]
[copy]Identity fraud expense reimbursement: adds about $25 a year.[/copy]
[copy]Animal liability coverage: adds about $40 a year.[/copy]
[copy]Equipment breakdown and service line coverage: adds about $50 a year.[/copy]
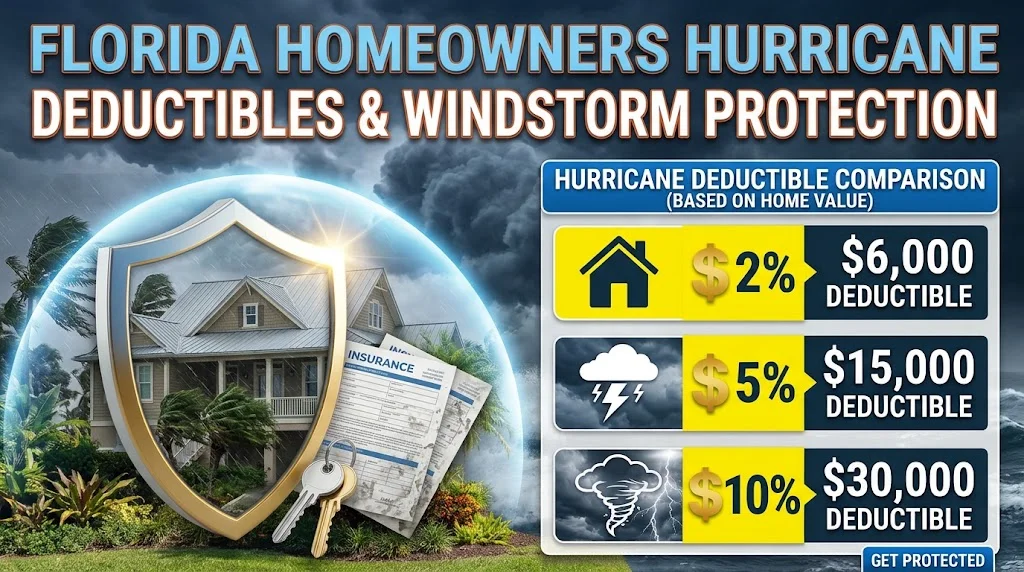
The hurricane deductible is a big lever. It is often a percent of your dwelling limit, not a flat dollar amount. A higher deductible lowers your premium but raises your out-of-pocket cost after a storm.
[copy]2% hurricane deductible ($7,000 on a $350K home): base premium of about $3,300.[/copy]
[copy]5% hurricane deductible ($17,500): saves about $400 a year.[/copy]
[copy]10% hurricane deductible ($35,000): saves about $800 a year.[/copy]
[copy]$1,000 all other perils (AOP) deductible: base premium.[/copy]
[copy]$2,500 AOP deductible: saves about $180 a year.[/copy]
[copy]$5,000 AOP deductible: saves about $300 a year.[/copy]
[copy]Windstorm deductible of 1% instead of 2%: costs about $350 more a year.[/copy]
[copy]Wind-only policy on a coastal $350K home: about $4,500 a year.[/copy]
[copy]Roof payment schedule on a 15-year-old roof: saves about $600 a year.[/copy]
[copy]Screened pool enclosure coverage of $25,000: adds about $140 a year.[/copy]
[copy]Home business coverage of $10,000: adds about $90 a year.[/copy]
[copy]Home systems protection add-on: adds about $45 a year.[/copy]
[copy]Condo loss assessment coverage of $50,000: adds about $40 a year.[/copy]
[copy]Landlord loss of rents coverage for 12 months: adds about $150 a year.[/copy]
How to Compare Rates and Save Money on Florida Home Insurance
Two identical homes can get very different home insurance quotes. Roof age, wind mitigation features and claims history drive most of the gap.
Comparing Florida homeowners insurance quotes can help you protect your property and enjoy greater financial peace of mind, but life is also about making memories beyond home. Whether you’re planning your next getaway or dreaming of new destinations, explore these inspiring short travel quotes to spark your wanderlust and celebrate the joy of every journey.
Start with the rate factors below. Each shows a sample price for a $350,000 home.
[copy]Roof 0 to 5 years old: about $3,000 a year.[/copy]
[copy]Roof 6 to 10 years old: about $3,400 a year.[/copy]
[copy]Roof 11 to 15 years old: about $4,100 a year.[/copy]
[copy]Roof 16 to 20 years old: about $5,200 a year.[/copy]
[copy]Roof over 20 years old: may be declined or priced above $6,500 a year.[/copy]
[copy]Home built after 2002: about $3,200 a year.[/copy]
[copy]Home built in the 1990s: about $3,900 a year.[/copy]
[copy]Home built before 1980: about $5,000 a year.[/copy]
[copy]Concrete block construction: about $3,300 a year.[/copy]
[copy]Wood frame construction: about $4,200 a year.[/copy]
[copy]Good credit-based insurance score: about $3,300 a year.[/copy]
[copy]Fair credit-based insurance score: about $3,900 a year.[/copy]
[copy]Poor credit-based insurance score: about $4,800 a year.[/copy]
[copy]Claims-free for five years: about $3,300 a year.[/copy]
[copy]One claim in the last three years: about $4,000 a year.[/copy]
[copy]Within one mile of the coast: about $5,800 a year.[/copy]
[copy]Five miles from the coast: about $4,000 a year.[/copy]
[copy]Twenty miles inland: about $3,100 a year.[/copy]
[copy]Fenced pool with safety features: adds about $150 a year.[/copy]
[copy]Rebuild cost up 10%: premium rises about $330 a year.[/copy]
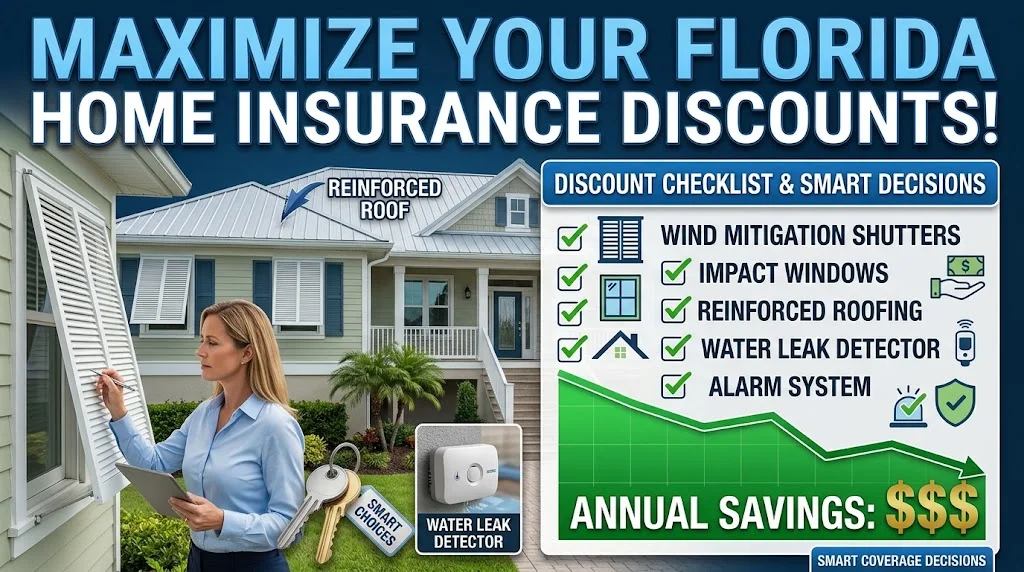
Discounts can cut a bill fast. A wind mitigation inspection proves your home’s storm features to the insurer. Florida homeowners often see the biggest savings here.
[copy]Wind mitigation inspection costs about $100 to $150 and can pay for itself in year one.[/copy]
[copy]Hurricane shutters on all openings: saves about $700 a year.[/copy]
[copy]Impact-rated windows and doors: saves about $900 a year.[/copy]
[copy]Hip roof shape: saves about $450 a year.[/copy]
[copy]Roof-to-wall straps: saves about $350 a year.[/copy]
[copy]Secondary water resistance on the roof: saves about $150 a year.[/copy]
[copy]Monitored burglar alarm: saves about $165 a year.[/copy]
[copy]Fire alarm: saves about $100 a year.[/copy]
[copy]Fire sprinklers: saves about $150 a year.[/copy]
[copy]Water leak detector: saves about $75 a year.[/copy]
[copy]Claims-free discount: saves about $200 a year.[/copy]
[copy]Bundle home and auto: up to 10% off, about $330 on a $3,300 home policy.[/copy]
[copy]Roof under five years old: saves about $400 a year.[/copy]
[copy]Paperless policy: saves about $25 a year.[/copy]
[copy]Pay in full: saves about $100 a year.[/copy]
Citizens Property Insurance vs Private Insurers in Florida
Citizens Property Insurance is Florida’s state-backed insurer of last resort. It covers homes that private companies won’t write.
Citizens often costs more for the same home, and its rules push people back to the private market.
Never pick a policy by price alone. Compare the deductible, replacement cost terms, exclusions and the insurer’s financial strength rating. Check ratings with AM Best and the Florida Office of Insurance Regulation.
Also check your dwelling limit. Industry reports say more than half of U.S. homes are underinsured. Insure your home for at least 100% of its estimated rebuild cost.
Here is how three quotes for the same home can differ.
[copy]Quote A: $4,200 with a 5% hurricane deductible and a roof payment schedule.[/copy]
[copy]Quote B: $4,900 with a 2% hurricane deductible and full roof replacement cost.[/copy]
[copy]Quote C: $6,300 with a 2% hurricane deductible, extended replacement cost and water backup.[/copy]
[copy]A $700 saving can vanish if the deductible is $10,000 higher after a storm.[/copy]
[copy]Same home, state-backed insurer of last resort: about $5,100. Private insurer: about $4,300. Compare both.[/copy]
[copy]A $2,500 AOP deductible plus a 5% hurricane deductible can cut a $4,900 quote to about $4,000.[/copy]
[copy]A $4,900 home quote with a 10% bundle discount: about $4,410.[/copy]
[copy]An independent agent who shops five insurers may find a $2,100 gap between the lowest and highest quote.[/copy]
[copy]Renewal at $4,400 versus a fresh quote at $3,800: shop again each year.[/copy]
[copy]A $4,900 quote can fall to about $3,700 after adding a wind mitigation report.[/copy]
Follow these steps to get a Florida homeowners insurance quote.
- Find your home’s replacement cost and roof age.
- Order a wind mitigation inspection.
- Request at least three quotes online or through an independent agent.
- Match the same limits and deductibles on each quote.
- Ask about every discount before you sign.
FAQs
What is the average cost of home insurance in Florida?
Published averages range from about $5,800 to over $8,000 a year, depending on the study. Your rate depends on your ZIP code, roof age, coverage limits and deductible.
How much home insurance do I need in Florida?
Insure your dwelling for its full rebuild cost. Set other structures near 10%, personal property near 50% and loss of use near 20% of that limit. Pick liability that matches your assets.
Is home insurance required in Florida?
No, state law does not require it. But if you have a mortgage, your lender will almost always require coverage. See the Florida CFO consumer guide.
What does home insurance not cover in Florida?
Standard policies exclude flood and storm surge. They also exclude earthquakes, sinkholes (unless added), pest damage and most mold. Damage in a long-vacant home may also be excluded.
What factors affect home insurance rates in Florida?
Location, rebuild cost, roof age, construction type, claims history, deductible, safety features and credit-based insurance score all matter. Florida insurers may use credit-based scores to set rates.
How can I get cheap homeowners insurance in Florida?
Compare at least three quotes. Raise your deductibles, get a wind mitigation inspection and bundle home and auto. Ask for every discount and re-shop at each renewal.
Conclusion
Florida home insurance costs a lot, but you can lower the bill. Compare quotes, match coverage to your rebuild cost and claim every wind mitigation discount.

Kashif Abroy is the author and content creator behind ShakespeareQuotess.com, a website dedicated to the timeless words, wisdom, and literary legacy of William Shakespeare. His goal is to make Shakespeare’s remarkable words accessible to modern readers, whether they are students, literature enthusiasts, writers, or anyone looking for inspiration and a deeper understanding of life